
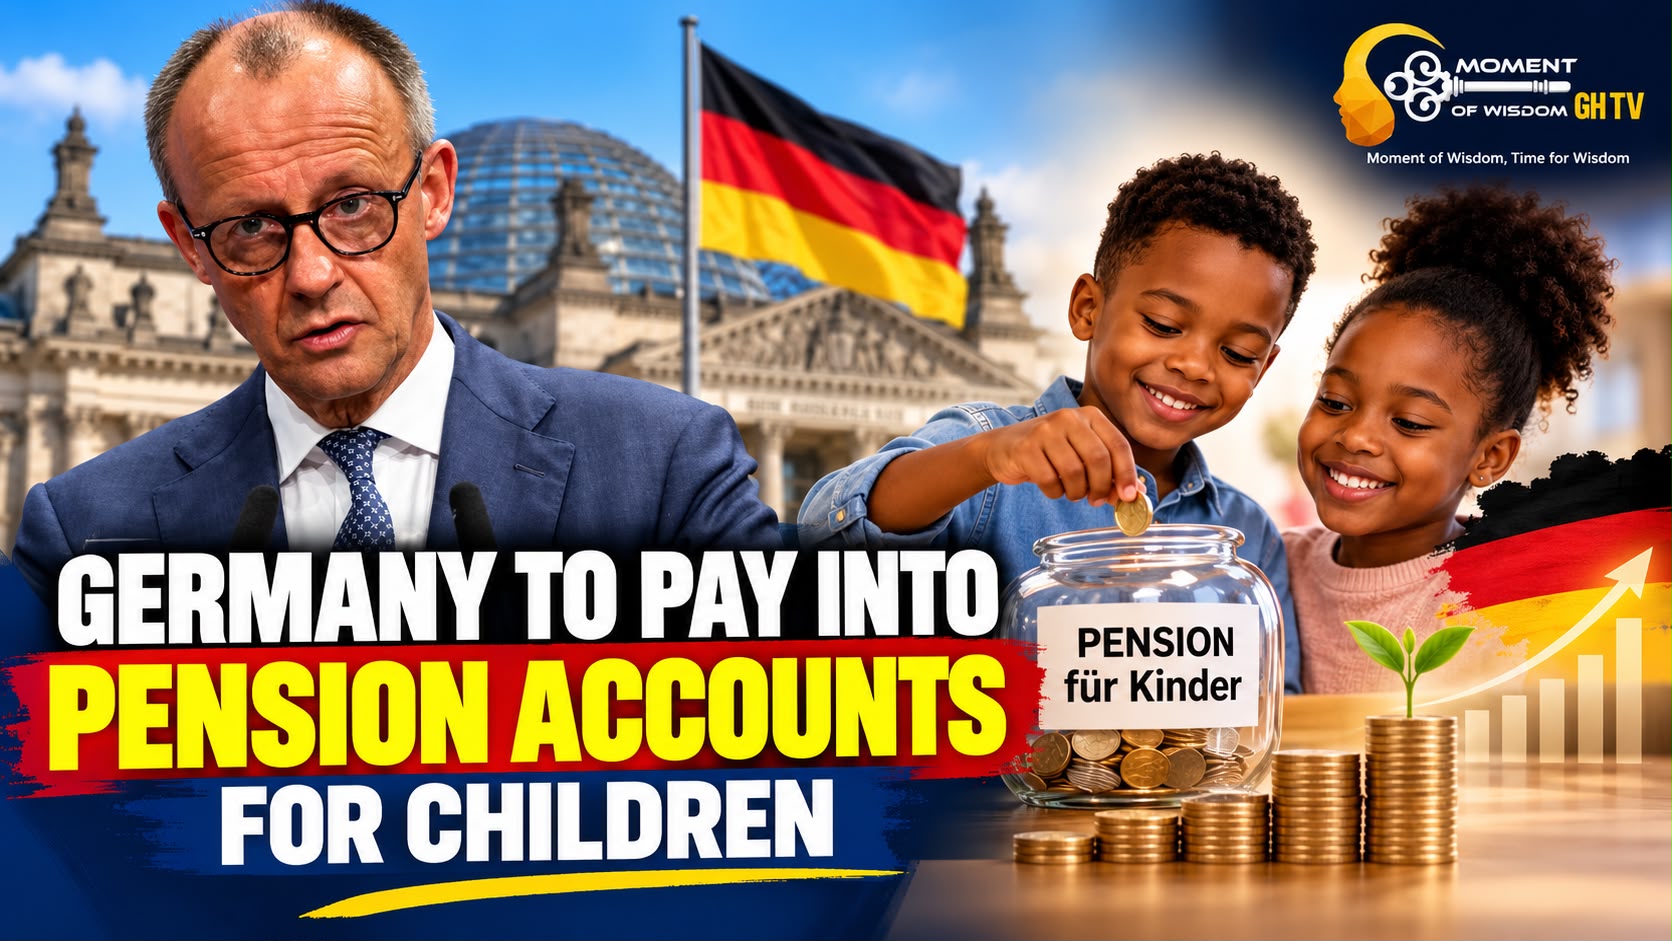
Germany is taking steps towards a major reform of its retirement savings system, with plans to introduce government-funded pension investment accounts for children.
The initiative, known as Frühstart-Rente (Early Start Pension), is intended to encourage long-term savings, introduce young people to investment opportunities and help future generations prepare financially for retirement.
The proposal represents a shift towards supplementing Germany’s traditional pension system with investment-based savings.
Under the proposed arrangement, the German government would contribute money into individual retirement savings accounts for eligible children.
Rather than keeping the funds entirely in ordinary savings accounts, the money would be invested in financial markets, allowing it to potentially grow over several decades.
The initiative aims to give children an early financial foundation before they enter employment.
However, investment returns are not guaranteed, and the value of market-based savings can rise or fall.
On Friday, 16 October 2026, Germany’s Bundestag approved the Early Start Pension legislation, with support from the governing CDU/CSU and SPD parties.
The Greens and The Left voted against the legislation, while the AfD abstained. The measure still requires approval from the Bundesrat before completing the legislative process.
Under the new scheme:
-
€10 per month will be contributed by the government for eligible children.
-
Contributions will run from age six until age 18.
-
The money will be invested in retirement savings accounts rather than paid directly to families.
-
Parents and relatives may make additional contributions, subject to applicable limits.
-
The programme will initially cover children born in 2020, with subsequent birth cohorts added progressively.
The government intends the scheme to begin operating in January 2027.
For Ghanaian families and other migrant households residing in Germany, the initiative could provide another opportunity to build long-term financial security for their children.
However, parents should understand that the programme is not an immediate cash benefit like Kindergeld. The money is earmarked for retirement savings and generally cannot be withdrawn for everyday household expenses.
Families should also check the final eligibility requirements and implementation arrangements before opening accounts.
Germany faces long-term challenges involving an ageing population, retirement financing and the sustainability of its pension system.
Supporters believe that introducing children to investment-based retirement savings could improve financial literacy and help young people benefit from decades of potential compound growth.
Critics have questioned whether the proposed monthly contribution is sufficient and whether investment-based retirement schemes expose families to financial market risks.
The German government estimates that the scheme could cost approximately €411 million annually by 2030.
The reform raises an important question for policymakers worldwide: Should governments begin investing in children’s retirement security long before they enter the workforce?
Germany’s initiative offers an interesting model for countries examining how to combine public pension protection, private savings and financial education.
Nevertheless, the programme’s success will depend on effective implementation, fair access, reasonable investment costs and long-term financial performance.
For families, the central message is clear: financial planning for old age can begin much earlier than adulthood.
Moment of Wisdom, Time for Wisdom.
Website: www.momentofwisdomgh.com

